


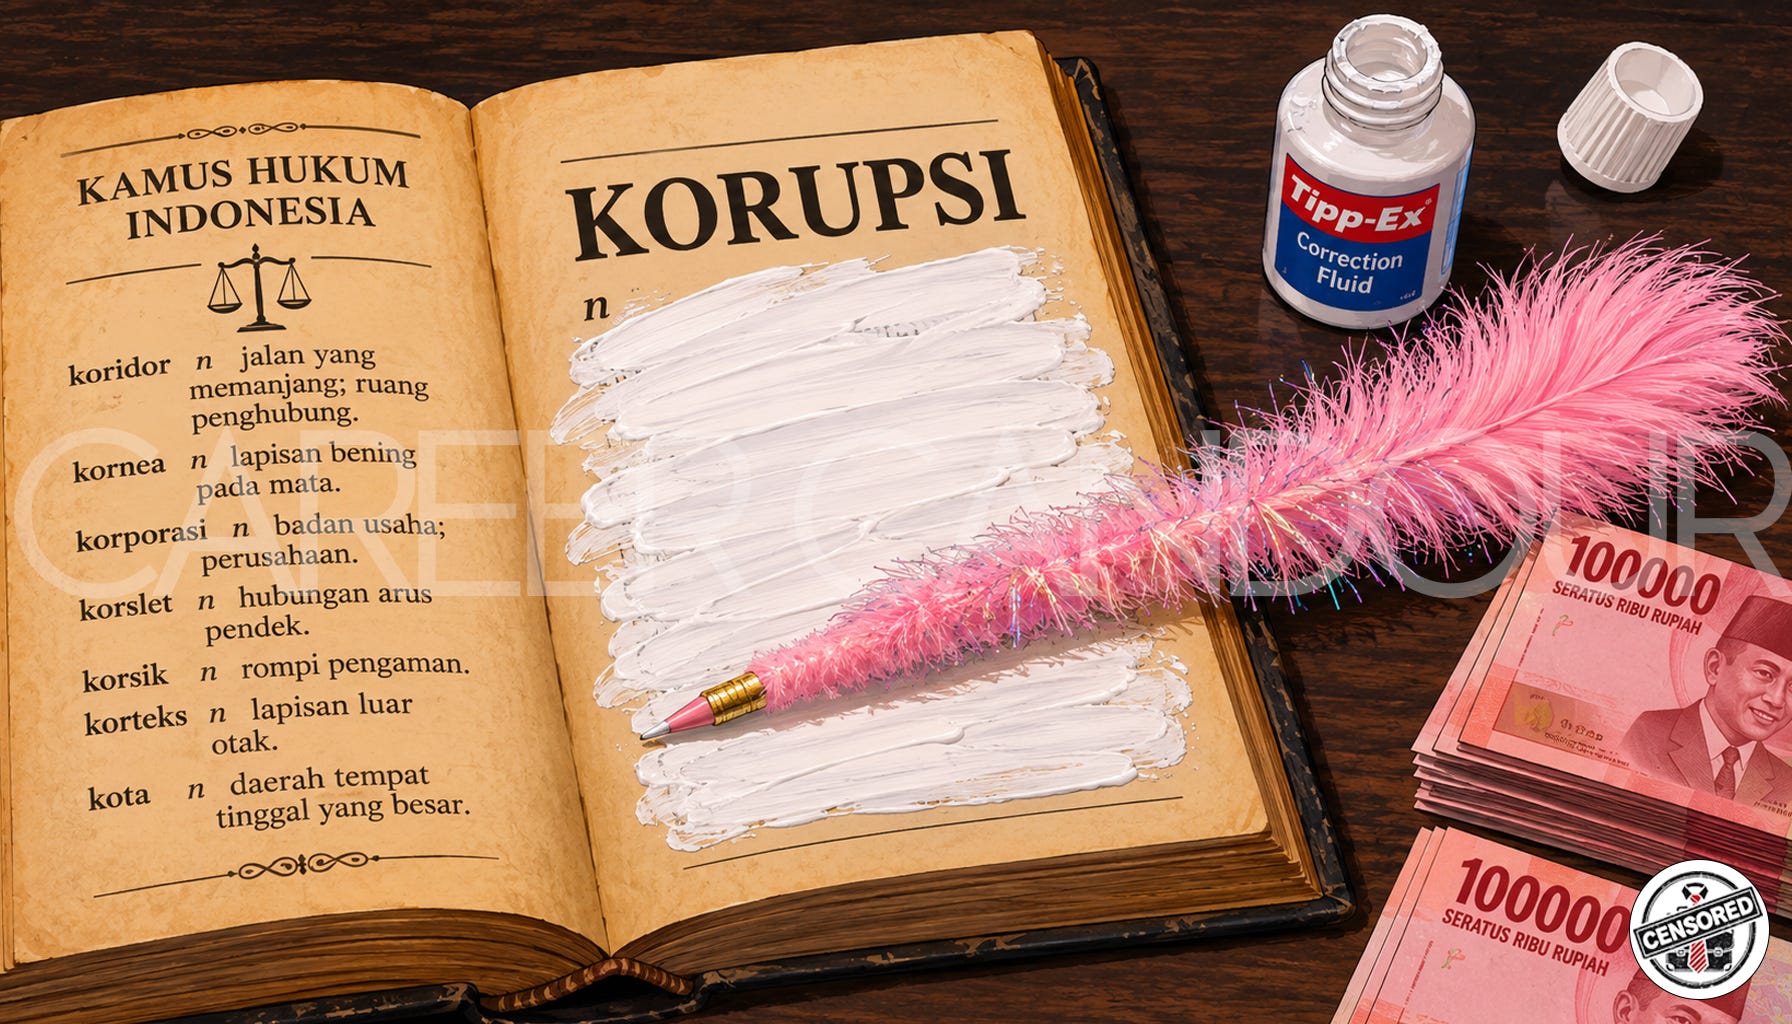
Last week outside Jakarta’s Merdeka Palace, General Luhut Binsar Pandjaitan did something that few seasoned observers of Indonesian statecraft could have anticipated: he offered the assembled press corps an impromptu seminar on comparative international public law.
General Luhut is not by nature an academic. Over the course of the past decade, the retired special forces general, former coordinating minister, and now head of President Prabowo Subianto’s National Economic Council has served as the republic’s ultimate bureaucratic field marshal. He is the man the state dispatches when:
A Chinese-backed high-speed railway runs over budget,
Nickel smelters require executive clearance, or
When foreign dignitaries must be reminded of Indonesia’s strategic heft.
He is, in short, a man of relentless operational execution, rarely troubled by the finer philosophical points of multilateral jurisprudence.
Yet there he stood, fresh from consultations with President Prabowo, declaring that the time had come to dismantle the central pillar of Indonesia’s post-Suharto anti-corruption architecture.
The state, the General explained, had to harmonize its criminal law with the United Nations. Under the “UN Charter,” by which he meant the United Nations Convention Against Corruption (UNCAC), the offense of corruption is fundamentally defined by the act of bribery. It does not, he noted, bother itself with the parochial concept of “State Financial Loss” (kerugian keuangan negara). Indonesia’s obsession with tallying up lost public funds was a historical eccentricity that was needlessly terrorizing state officials and scaring off institutional capital.
It was a high-minded, modernizing, and cosmopolitan performance. It was also, to anyone acquainted with the political economy of modern Jakarta, a moment of political theater.
For twenty years, Indonesia has treated the United Nations Convention Against Corruption with cautious indifference. The convention’s central provisions, such as unexplained wealth, the criminalization of illicit enrichment, and the prosecution of political influence peddling, have gathered dust in committee rooms for two decades.
Why, then, this sudden outbreak of multilateral piety? Why had the cabinet discovered a thirst for international compliance?
The answer was neither theoretical nor altruistic. As the General let slip moments later: “This burdens entities like Danantara in making business decisions, where naturally, any business carries risks.”
The legal machinery built to hunt post-authoritarian thieves had just collided head-on with Indonesia’s new era of state capitalism.
The Cost of Bad Timing
To understand the sudden desire to amend Indonesia’s legal dictionary, one must first appreciate the architecture of its anti-corruption laws. In most mature jurisdictions, sending an executive or a politician to prison for corruption requires proving a corrupt mind (mens rea) and a corrupt act: a suitcase of banknotes, or an illicit equity transfer.
In Indonesia, the state decided long ago that chasing paper trails through offshore tax havens was an exhausting enterprise. Instead, under Articles 2 and 3 of Law No. 31/1999 (the Anti-Corruption Law / UU Tipikor), and their modern twins in Articles 603 and 604 of the new Criminal Code (KUHP), the state granted itself a shortcut: State Financial Loss.
If an official or state-enterprise director commits an act that violates an administrative regulation (perbuatan melawan hukum), and that act results in a measurable deficit to the state purse or a state-owned enterprise, a crime of corruption has occurred. Critically, prosecutors do not need to prove that you took a single rupiah for yourself. They need only summon an auditor from the Supreme Audit Agency (BPK) or the Development and Finance Comptroller (BPKP), point to a line item that went down instead of up, identify a procedural memo that lacked an official stamp, and ask the court for a twelve-year sentence.
For years, this sledgehammer was celebrated as a necessary weapon against a deeply entrenched culture of bureaucratic looting. But in recent months, the criminal justice system has criminalized standard corporate losses.
Consider the trial of Indonesia’s state-backed venture capitalists. Earlier this year, the Jakarta Corruption Court sentenced Donald Wihardja, the former chief executive of Telkom’s MDI Ventures, to five years’ imprisonment, and Nicko Widjaja, the former head of BRI Ventures, to three years. Their transgression? They had deployed state enterprise capital into TaniHub, a domestic agritech startup that subsequently suffered a commercial collapse amid market downturns and internal governance fraud.
The judges took great care in their written verdicts to confirm the obvious: neither Donald, nor Nicko, nor their investment officers had received a single kickback, bribe, or illicit flow of funds. They had not enriched themselves.
Yet they were marched off to prison nonetheless.
By failing to detect that a private third-party startup was misstating its internal metrics, the fund managers had breached their “duty of prudence” (prinsip kehati-hatian). Under Article 2, this single oversight turned a standard investment loss into a charge of corruption.
Venture capital is an asset class built entirely upon the power-law distribution: seven out of ten seed-stage bets will fail, two will break even, and one outsized winner will pay for the fund. By applying the state-loss doctrine to venture equity, the Indonesian judiciary effectively ruled that investing public money in innovation is entirely legal…provided that no company in the portfolio ever loses money.
A similar structural bluntness defined the prosecution of former Education Minister Nadiem Makarim over a multi-trillion-rupiah procurement of Chromebook laptops. Long before the indictment was drafted, rumors circulated of corporate ecosystem favoritism, cozy relationships with tech giants, and policies that aligned a little too neatly with certain tech companies.
Yet when the state brought its case under Article 604 of the penal code, it bypassed proving an institutional conflict of interest or an illicit agreement.
Instead:
Prosecutors argued that the laptops were unsuited to the erratic electricity and patchy internet of Indonesia’s border schools,
Calculated the difference between the budget spent and the utility gained,
Declared a Rp 1.5 trillion “state financial loss,” and secured a heavy custodial sentence.
The message was simple: the state does not need to prove you are corrupt; it only needs to prove that your business decisions resulted in a financial loss for the government.

Enter Danantara
To view this legal friction as an injustice upon a handful of corporate suits is to miss the scale of what the Indonesian state is preparing to do next.
Chartered under President Prabowo’s administration, Danantara is designed to be Indonesia’s answer to Singapore’s Temasek and GIC rolled into one. It is a sovereign super-holding company built to consolidate the state’s crown jewels into a financial colossus managing an estimated $600 billion in assets.
Unlike the traditional bureaucracy, Danantara is intended to behave like a world-class asset manager. It is expected to:
Underwrite multi-billion-dollar domestic downstream nickel and green-energy consortia,
Fund big infrastructure bets, and
Pump capital into high-growth domestic enterprise.
It is expected to take colossal, institutional risks.
This is where the political economy becomes personal.
Sitting at the apex of macroeconomic strategy as Chairman of the National Economic Council is General Luhut.
Steering the investment strategy of Danantara as its Chief Investment Officer is Pandu Patria Sjahrir.
Mr. Sjahrir is not an administrative bureaucrat promoted through the civil service ranks. He is:
A founding partner at AC Ventures,
A former executive at energy firm TBS Energi Utama, and
One of the most visible elder statesmen of Indonesia’s venture ecosystem.
He is also General Luhut’s nephew—the son of the General’s sister, the diplomat Nurmala Kartini Sjahrir, and the late celebrated economist Sjahrir.
On paper, Pandu Sjahrir’s pedigree is tailor-made for running a sovereign investment shop. He speaks the language of private equity. But his appointment illustrates the institutional crisis facing Indonesia.
Danantara has launched during a period of considerable capital-market turbulence.
The Jakarta Composite Index (IHSG) has wobbled under shifts in foreign investor sentiment;
Global index providers have raised nervous eyebrows regarding liquidity and corporate governance; and
Danantara’s own consolidated reporting and audits have taken time to emerge.
Now, place that commercial reality next to the judicial precedent set in the TaniHub trials.
If Danantara’s investment committee approves a $500 million equity injection into a domestic green-hydrogen consortium, and global energy prices shift, wiping 30% off the asset’s valuation, what happens?
Under the status quo of Indonesian law, an ambitious prosecutor at the Attorney General’s Office or the KPK does not need to find a Swiss bank account belonging to the fund managers. They need only find:
That Danantara skipped a sub-clause in an internal procurement manual,
Cross-reference it with the asset markdown,
Label the negative delta a “State Financial Loss,” and
Dispatch police cruisers to Danantara’s headquarters.
General Luhut’s passing remark at the Palace gates, that state loss provisions “burden entities like Danantara in doing business,” was a clear-eyed diagnosis of an operational hazard. The state was building a 21st-century sovereign investment titan, but housing it inside a legal garage governed by the penal sensibilities of 1999.
If you put a venture capitalist in charge of the state’s crown jewels, you must ensure that a routine market down-cycle does not end with his investment committee serving five-to-seven years in a West Java penitentiary.

The Gospel According to the UN
Faced with this institutional emergency, the administration’s technocrats required a justification of unimpeachable moral authority. They could hardly approach the public and say, “We need to change the law because our new sovereign fund is terrified of the stock market.”
And so, the political establishment opened the drawer marked Multilateral Treaties and retrieved the United Nations Convention Against Corruption.
The argument presented by the Palace was simple: Indonesia, in its boundless desire to be an attractive destination for foreign capital and a responsible member of the global community, must modernize. The UN framework defines corruption as bribery—the corrupt transaction between an official and a private interest. It contains no awkward, catch-all offenses regarding “state financial loss.” Therefore, to align with the civilized world, Indonesia must strike state loss from its books.
It is an argument of brass-necked brilliance. It is also an intellectual fiction that relies entirely on the assumption that nobody in Indonesia has read the convention.
Ratified by Indonesia via Law No. 7/2006, the United Nations Convention Against Corruption is an integrated matrix of anti-graft enforcement. While it is true that the treaty does not define corruption around the parochial concept of domestic state budget deficits, it compensates for this with a battery of enforcement mechanisms designed to render large-scale financial theft impossible:
Article 20 (Illicit Enrichment): The convention suggests that states criminalize “a significant increase in the assets of a public official that he or she cannot reasonably explain in relation to his or her lawful income.” This is the weapon of choice in Hong Kong, Singapore, and across the common-law world. It reverses the evidentiary burden: if a mid-level director-general earning $1,500 a month owns four penthouses in South Jakarta, the state seizes the penthouses and imprisons the director-general without needing to prove which specific kickback funded which specific bedroom.
Article 18 (Trading in Influence): It explicitly criminalizes the brokering of political connections, family relationships, and access for private commercial benefit.
Article 54 (Asset Recovery): It mandates the establishment of non-conviction-based civil forfeiture, which allows prosecutors to reclaim proceeds of graft without navigating the criminal courts.
For twenty years, successive Indonesian parliaments and cabinet coalitions have treated these specific articles with panic.
The Asset Forfeiture Bill (RUU Perampasan Aset) has languished in the legislative docket for over a decade, buried by lawmakers who understand that an audit of their family trusts and luxury vehicle collections would decimate the front benches. The criminalization of Illicit Enrichment has been flatly ignored, precisely because half the political elite would likely be unable to survive a review of their official asset declarations (LHKPN).
The selective amnesia on display is breathtaking. The state wishes to load up on the immunities that shield state-backed fund managers from commercial liability, while turning away from the provisions that would require the political class to explain where their money came from.

Lex Favor Reo
(The Sukamiskin Panic)
Had the administration’s strategy ended with a clean, technocratic rewrite of the law, it might have sailed through a compliant parliament. But Indonesian jurisprudence contains a built-in trapdoor.
It is known to every first-year law student as the principle of Lex Favor Reo (The More Favorable Law).
Codified in Article 1, Paragraph 2 of the old Criminal Code and preserved with absolute clarity in Article 3 of the New Criminal Code (Law No. 1/2023), the rule states:
If there is a change in the legislation after an act was committed, the provisions most favorable to the defendant shall apply.
Crucially, Paragraph 2 adds that if an act is decriminalized, any ongoing prosecution is immediately dismissed, and for those already convicted, the execution of their sentences is extinguished.
Consider the immediate, chaotic domino effect:
At the Supreme Court, former Minister Nadiem Makarim’s cassation (kasasi) appeal is currently pending. He was convicted under Article 604—the state loss article. Because his verdict is not yet legally final (inkracht), an erasure of state financial loss would require the Supreme Court to instantly declare that the crime for which he was sentenced no longer exists. Unless prosecutors could conjure up a direct cash bribe that they had failed to prove over two years of trial, he would be legally entitled to a complete acquittal (vonis bebas).
Over at Sukamiskin Prison in Bandung the reaction would be celebratory.
For a quarter of a century, most corruption convictions secured by the KPK and the Attorney General’s Office have relied on the state-loss doctrine of Articles 2 and 3. In the majority of those cases, prosecutors proved missing budget billions, rigged specifications, or inflated state enterprise purchases, rather than chasing a wiretapped cash bribe.
If state loss is struck from the penal code, it would potentially open the prison gates for an entire generation of convicted regional regents, provincial governors, procurement racketeers, and state enterprise directors.
Any convict sitting in a cell whose indictment rested on causing a deficit to the state would have immediate constitutional grounds to file a Judicial Review (Peninjauan Kembali) demanding their sentence be vacated.
The public pushback that erupted across Jakarta was immediate. The KPK’s leadership, lawmakers in Commission III of the House of Representatives (DPR), and anti-corruption watchdogs like ICW and PUKAT UGM sounded alarms. The government had set out to build an administrative safety net for sovereign fund managers, but in doing so, had designed an institutional jailbreak mechanism for the entire convicted elite.

Good Faith on Paper
(From Sledgehammer to Scalpel)
Faced with the prospect of dismantling twenty years of anti-corruption jurisprudence, the administration executed “Cek Ombak” (testing the waves).
An elder statesman floats a radical policy trial balloon to gauge the public’s pain threshold;
When the public, the press, and the legal watchdogs respond with outrage, the executive beats a hasty retreat to a pre-prepared middle ground that achieves the original objective anyway.
Within forty-eight hours of General Luhut’s palace address, the National Economic Council issued a formal statement of clarification.
Nobody, the General insisted, was proposing to abolish Articles 2 and 3. The state was not going to strip “state loss” from the Anti-Corruption Law, nor from Articles 603 and 604 of the new Criminal Code. The state-loss doctrine would remain firmly on the statute books.
Instead, DEN explained, the administration was proposing to “refine the methods of proof” (penyempurnaan pembuktian) and enshrine the Business Judgment Rule (BJR) and Policy Judgment Rule (PJR) directly into criminal procedure. Furthermore, the state would look into adopting narrow UNCAC offenses, such as the criminalization of bribing foreign public officials.
It was a pivot from a sledgehammer to a scalpel.
The problem that has haunted state-owned enterprises for decades is that the Business Judgment Rule has historically offered little protection inside a criminal courtroom. Indonesian prosecutors and judges have routinely operated under the doctrine of *lex specialis*, asserting that criminal anti-corruption law overrides mere corporate statutes. When money went missing, the corporate defense of “good faith” was discarded by judges who viewed any procedural imperfection as proof of criminal negligence.
By proposing to write the Business Judgment Rule directly into criminal law, the administration is seeking to accomplish through procedural nuance what it failed to achieve through statutory abolition.
The new battleground will be over who gets to claim the shield of administrative discretion:
If an investment board can establish that it held a formal meeting, filed an internal risk report, and took advice from an investment consultancy, does that create an absolute, bulletproof presumption of “good faith”?
If so, how will prosecutors ever distinguish between a bona fide high-risk sovereign investment that went belly-up, and an elaborate, multi-layered insider scheme designed to enrich an oligarchic patron?
In a country with a fiercely independent, technically sophisticated judiciary, such a balance is difficult to strike. In Indonesia, where the lines between state authority, business conglomerates, and familial dynasties are deeply blurred, embedding an absolute statutory defense of “executive good faith” without simultaneously passing aggressive checks on illicit enrichment risks building an impenetrable legal wall around sovereign capital.

Indonesia is an ambitious nation attempting to run two contradictory developmental models simultaneously.
On one hand, it dreams of being Singapore or the Emirates:
Deploying hundreds of billions of dollars through state-directed capitalism,
Consolidating its banks and miners into sovereign vehicles like Danantara,
Building tech ecosystems,
Taking minority equity stakes in foreign supply chains, and
Driving economic growth through aggressive, market-facing risk.
This model requires speed, flexibility, and, above all, the commercial freedom to fail.
On the other hand, the Republic remains governed by an anti-corruption architecture conceived in the trauma of the 1997 Asian Financial Crisis and the fall of the New Order.
The friction between these two systems was tolerable as long as state enterprises stuck to building toll roads and managing domestic telecommunications monopolies. But the moment the state created venture funds like MDI and sovereign wealth funds like Danantara, the structural collision became inevitable. You cannot construct a $600-billion sovereign private-equity powerhouse while threatening to indict its leadership every time an equity investment prints a quarterly markdown.
The tragedy of the current moment is that Indonesia’s political leadership has identified a real, crippling administrative defect, but has chosen to fix it through elite self-preservation.
The state-loss doctrine is an archaic substitute for genuine financial investigation.
It did lead to the unjust criminalization of honest venture capitalists who took zero bribes but saw their investments collapse.
It has paralyzed honest civil servants who are now terrified of signing procurement orders for fear of landing in a prison cell.
A modernization of Indonesian anti-corruption law would solve this:
Enshrine a robust, statutory Business Judgment Rule that protects bona fide commercial risk from criminal prosecution.
In exchange, pass the complete, unadulterated United Nations Convention Against Corruption: criminalize Illicit Enrichment, outlaw Trading in Influence, and enact the Asset Forfeiture Bill.
Such a compromise would protect the venture capitalists and sovereign fund managers when their investments fail in the market, while guaranteeing that any executive or politician who amasses an unexplained fortune while managing state resources is stripped of their wealth and marched straight to a prison cell.
Yet that is the one reform that will never happen.
Instead, the Republic will watch a flurry of procedural revisions designed to insulate the sovereign wealth fund and its well-connected custodians, leaving the rest of the country’s archaic penal machinery firmly in place. Indonesia will continue to celebrate its newfound respect for international law, happily quoting the United Nations on the virtues of commercial freedom, while leaving the pages on public accountability safely uncut.
StratEx - Indonesia Business Advisory provides Indonesia-focused advisory and leadership intelligence for investors that need to understand what is really moving beneath the surface. Contact us for better visibility before making your next move in Indonesia.