


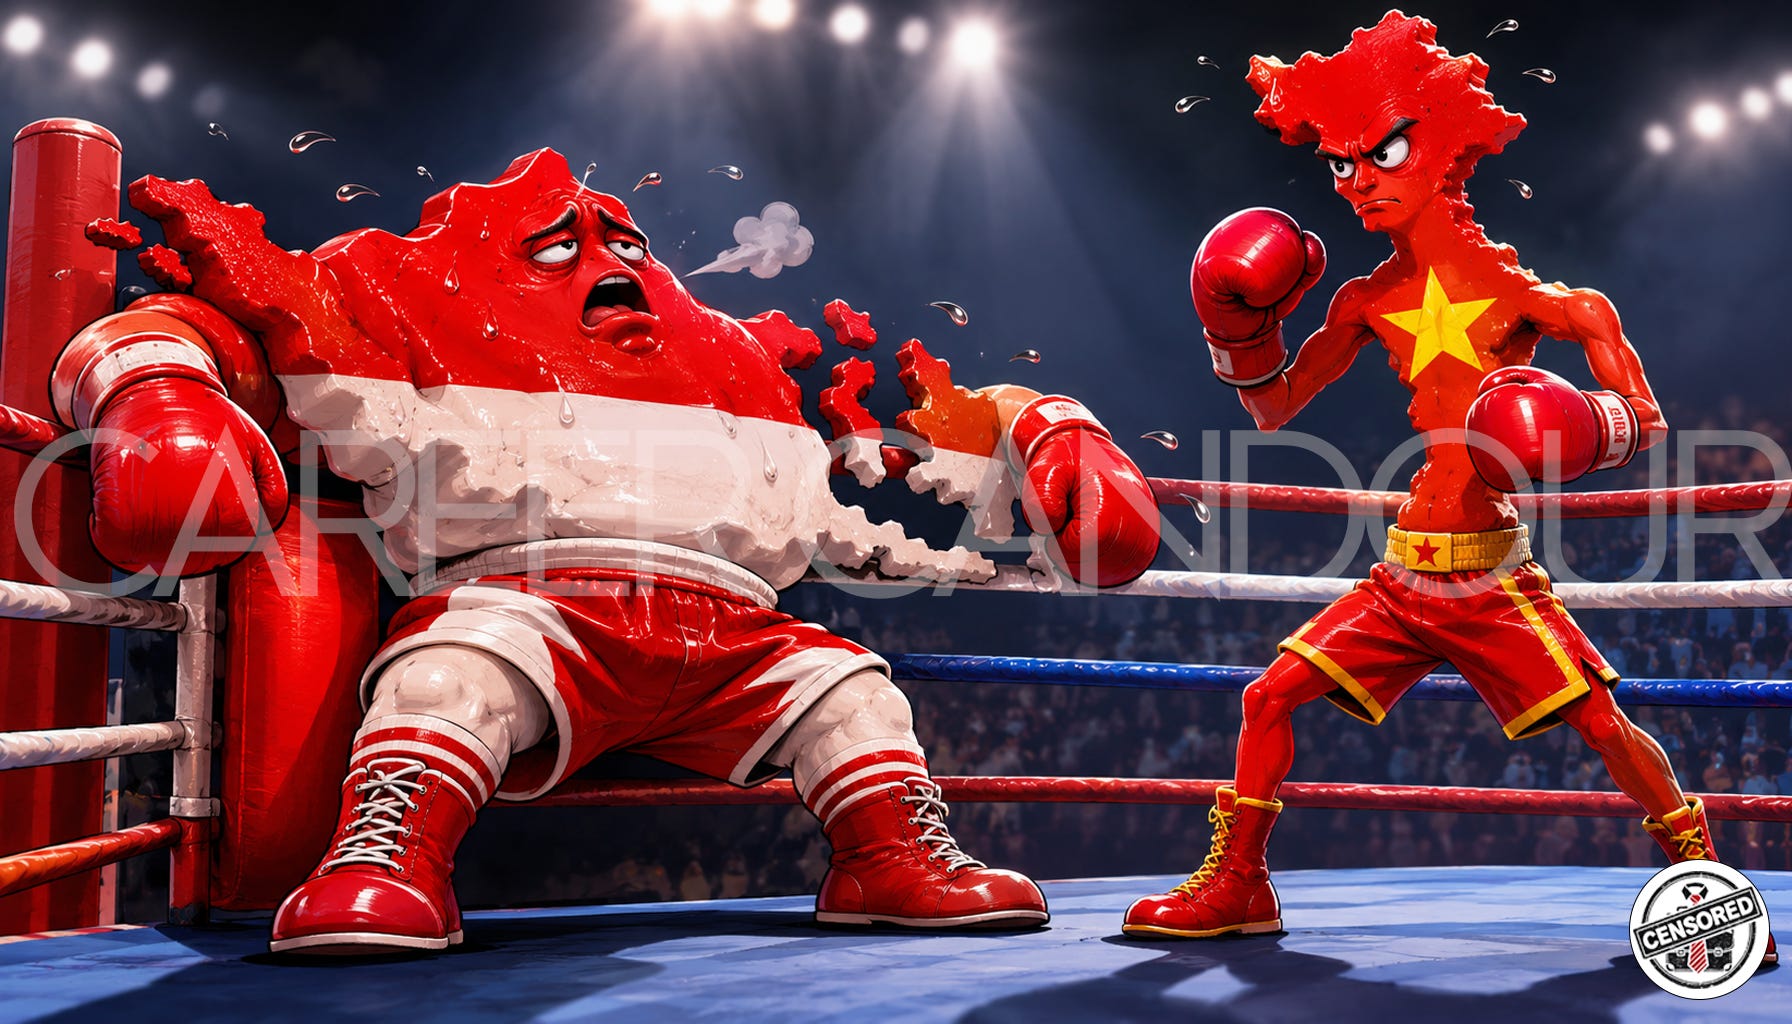
There’s a shift in the air when a giant realizes that it has been outpaced. It typically arrives disguised as an International Monetary Fund spreadsheet. When the Fund’s World Economic Outlook recently flashed the news that Vietnam was projected to overtake Indonesia in nominal GDP per capita, the collective response from Indonesia’s political establishment was an indignant clearing of throats, followed by a retreat behind aggregate accounting.
Indonesia, the Ministry of Finance whispered to friendly columnists, remains an economic colossus.
It is a proud G20 member;
Its headline gross domestic product sits near $1.48 trillion, while Vietnam’s is $540 billion.
Indonesia possesses roughly 280 million people to Vietnam’s 101 million.
It is a maritime empire, an anchor of regional geopolitics, and a market so gargantuan that consumer-goods conglomerates speak of it with reverence.
To suggest that Jakarta had been overtaken by Hanoi was, technically speaking, comparing apples to oranges.
Yet macroeconomic aggregates are the classic refuge of empires in relative decay. Divide the gross national harvest by the sheer volume of people tilling the soil, and a less flattering reality emerges: on a per-person productivity basis, a pencil-thin, post-communist strip of land that was still rationing rice when the Berlin Wall fell has sprinted past Southeast Asia’s undisputed heavyweight. Indonesia’s total economic heft remains intact simply because it has almost three times as many bodies. But the direction of travel is unmistakable. The tortoises of the Mekong have outpaced the swaggering hares of Java.
The 1997 Pivot
To grasp the scale of this, one must travel back to 1990, an era when the comparison would have seemed insane. Thirty-five years ago, Indonesia was a darling of the World Bank’s original “East Asian Miracle.” Flush with petrodollars, rubber concessions, and the iron-fisted political stability of General Suharto’s New Order, Indonesia boasted a nominal GDP per capita of $578. Vietnam, still bleeding from decades of slaughter, crippled by an American embargo, and emerging from the failed collective farming experiments of early socialism, was registering an income per head of roughly $99. The average Indonesian was nearly six times richer than the average Vietnamese. Jakarta had highway bypasses, satellite communications, and state-backed aerospace dreams; Hanoi had bicycle gridlock and rolling blackouts.
The pivot point came in the late 1990s, dictated by two entirely different responses to macro-financial ruin. When the Asian Financial Crisis swept through the region in 1997, Indonesia’s crony-capitalist financial system was exposed as an elaborate house of cards.
The rupiah collapsed from 2,500 to the dollar to beyond 15,000;
The economy contracted by 13.1% in a single year, and
Suharto’s thirty-year regime dissolved in street riots and bank runs.
The trauma broke Indonesia’s technocratic nerve. For the next decade, Jakarta turned inward, gripped by a newfound regulatory skepticism of global financial currents and developing a democratic political model where political power was redistributed among regional barons and oligarchic cartels.
Vietnam, observing the carnage from behind the protective moat of non-convertible currency controls and closed capital accounts, emerged from 1997 with its real growth rates more resilient . But its leadership extracted the opposite lesson. With far less mineral wealth or petrodollar cushions to bankroll its patronage networks, the Communist Party of Vietnam (CPV) deduced that its survival required submission to the disciplines of global trade. Lacking the natural resource endowments that permit Jakarta the luxury of self-absorption, Hanoi spent the 2000s signing bilateral trade pacts with Washington, slashing import tariffs, and knocking desperately on the door of the World Trade Organization until it was admitted in 2007. Indonesia spent the decade enjoying the unearned riches of a China-fueled commodity boom; Vietnam spent it learning how to manage industrial export zones without irritating foreign factory managers.

Geography Wins
Economic theory places enormous weight on agglomeration and transport friction but rarely has an archipelago paid so devastating a penalty for its geology. Indonesia’s islands are a postcard paradise and a logistics officer’s nightmare. Thanks to cabotage regulations, congested inter-island hubs, and port cartels, shipping a container of refrigerated goods from Ambon to Surabaya could potentially cost more than chartering that same container from Jakarta to Rotterdam. It is a domestic economy subjected to a perpetual, self-inflicted internal tariff.
Vietnam, by contrast, is shaped like an industrial conveyor belt. Its narrow, S-shaped landmass possesses thousands of kilometers of coastline facing the world’s busiest maritime shipping routes, linked together by an aggressive state program of highway and deep-water port construction. More crucially, its northern provinces share a land border with Guangdong and Guangxi. When the United States unleashed its tariff assault on Beijing in 2018, corporate supply-chain architects looked at Southeast Asia as a problem of transit times.
In the industrial corridors of Hải Phòng or Bắc Ninh, an assembly line manager can run out of a specialized sub-assembly bracket, place an order with a supplier in Dongguan or Shenzhen, and have the part cleared through the Friendship Pass border crossing and resting on the factory floor within twelve hours. To replicate that supply chain in West Java requires multi-day maritime customs clearance, the navigating of congested sea straits, and a prayer that Jakarta’s container terminals are not suffering from a localized strike or a sudden, unannounced ministerial import decree. Vietnam engineered its trade-to-GDP ratio to soar to around 190%, turning itself into one of the most open economies on Earth. Indonesia, safe inside its domestic moat, kept its trade openness ratio parked near 43%, looking suspiciously at foreign supply chains while wondering why foreign direct investors kept flying past Jakarta to land in Hanoi.

Who Makes What
The core of Vietnam’s per-capita success lies in the composition of what both nations produce. Economists are fond of invoking the “Smiling Curve,” the diagram showing that the lowest margins in global production lie in raw extraction and basic assembly, while the fat profits reside at the ends—in intellectual property and final branding. Confronted with this reality, Indonesia made a bet on geology: it decided to conquer the middle of the value chain by national fiat.
Under the banner of Hilirisasi (downstreaming), Jakarta banned the export of raw, unprocessed mineral ores. If foreign powers wanted Indonesia’s vast nickel, copper, and bauxite reserves to feed the electric vehicle revolution, they would have to build the smelters on Indonesian soil. On the surface, the policy looked like a blow against neo-colonial commodity exploitation. Tens of billions of dollars, predominantly from Chinese state-linked firms, poured into industrial parks in Central Sulawesi and the Maluku islands. Mineral export figures jumped, and government ministers delivered speeches about Indonesia becoming an indispensable green-tech superpower.
Yet hilirisasi masks a deeper developmental malady: premature deindustrialization. Building a capital-intensive, coal-powered rotary kiln electric furnace to smelt nickel pig iron employs a small number of domestic engineers per billion dollars invested. It does next to nothing for the hundreds of thousands of high school graduates entering the labor force every year. Manufacturing as a share of Indonesia’s GDP has withered steadily, sliding from nearly 30% in the early 2000s to under 19% today.
Vietnam took the opposite path. It accepted its place at the bottom of the Smiling Curve and turned itself into the world’s master of the “screwdriver economy.” It made no immediate demands for domestic brand prestige; it just offered political stability, zero-tariff import zones for intermediate goods, and an army of remarkably efficient factory hands. Samsung alone arrived and steadily built a manufacturing empire that now accounts for roughly 15% of Vietnam’s entire export tally, joined shortly after by Foxconn, Luxshare, and Pegatron.
By 2018, Vietnam’s total merchandise exports overtook Indonesia’s. Today, an economy that is a fraction of Indonesia’s physical and demographic size routinely exports more than $400 billion worth of goods annually, leaving Indonesia’s resource-heavy export machine stranded around $270 billion. Vietnam’s model is precarious, since foreign-invested enterprises generate over 70% of those exports, and domestic value-add remains frustratingly thin, but it created an flywheel that generates formal wages, absorbs labor, and drags millions out of farming into high-throughput modern manufacturing.

Bureaucratic Theater
Politically, the two nations couldn’t be further apart. Indonesia operates under the logic of the democratic megaphone. Politics is an exercise in exuberant performance, dynastic alliances, and rhetorical visions. The current political catechism is Indonesia Emas 2045 (”Golden Indonesia 2045”), an official roadmap projecting that the republic will celebrate its centenary as a top-five global economy with high-income status. President Prabowo Subianto campaigned on a pledge to supercharge the economy to 8% annual growth.
To produce 8% growth, an economy burdened with an Incremental Capital-Output Ratio (ICOR) of roughly 6.8—meaning it requires almost seven dollars of investment to squeeze out a single dollar of additional GDP—would need to achieve an inordinate investment rate. Because Indonesia’s tax-to-GDP ratio remains anemic at about 12%, the state cannot finance this growth through public balance sheets without breaching its sacrosanct 3% statutory budget deficit limit.
Instead, the political machinery produces grand gestures:
Carving a multi-billion-dollar futuristic capital city, Nusantara, out of the malaria-prone jungles of East Kalimantan, or
Rolling out the nationwide Makan Bergizi Gratis (Free Nutritious Meals) program, a multi-billion-dollar scheme to distribute free milk and eggs to dozens of millions of schoolchildren.
It is economic policy conducted as a series of populist moral crusades, mediated by an oligarchic elite that derives its real wealth from coal mines, real estate concessions, and domestic banking monopolies.
In Hanoi, there are no TikTok campaign spectacles, because there are no real elections to contest. Governance is conducted through the Leninist administrative machinery of the five-year plan. The Communist Party does not justify its existence through charismatic populism; it justifies it through raw performance. If economic growth falters, the regime’s supreme narrative crumbles.
Yet Vietnam has its own institutional dysfunction. The late General Secretary Nguyễn Phú Trọng’s anti-corruption drive, Đốt Lò (”Blazing Furnace”), efficiently cleared out state presidents, deputy prime ministers, and prominent tycoons. The unintended consequence was a nationwide bout of administrative paralysis: local bureaucrats and provincial cadre chiefs, terrified that signing off on an infrastructure procurement contract might land them in a prison cell next to a disgraced real estate developer, just stopped signing documents. Public capex disbursements ground to a halt.
Yet even within this climate of administrative terror, the machine grinds on. The infrastructure gets built because failure to hit growth quotas carries an even more certain career death than signing a flawed land appraisal. When Vietnam reported a third-quarter GDP growth rate of 9.95%, the announcement was met in Hanoi not with parades or golden centenary sloganeering, but with the satisfaction of a factory manager whose shift has met its production quota.

The Ticking Clocks
Neither country, however, is on a smooth highway to economic paradise. Both are trapped in a race against structural time.
Indonesia’s crisis is one of human capital. For all the poetry written about its youthful demographic dividend, the republic’s education system is a slow-motion disaster. In round after round of the OECD’s Programme for International Student Assessment (PISA) tests, Indonesian fifteen-year-olds rank reliably towards the bottom globally for mathematics, reading, and science. A large proportion of Indonesian high school leavers are functionally innumerate.
This human capital bottleneck makes Indonesia’s dream of pivoting from raw mineral smelting to high-tech design a fantasy. You cannot build a domestic semiconductor, avionics, or precision machinery ecosystem when your labor force struggles with sixth-grade arithmetic. Indonesia’s massive youth cohort risks becoming an underemployed proletariat condemned to delivering iced coffee on scooters, staffing retail malls, and driving ride-share vehicles in a permanent informal sprawl.
Vietnam’s bottleneck is the opposite. Its workforce is exceptionally capable, but it is rapidly running out of people. In the same PISA metrics where Indonesian students flounder, Vietnamese teenagers perform far better. The Vietnamese state succeeded in building a disciplined, mathematically competent base of human capital that absorbs technical training.
The catch is that Vietnam is getting old with terrifying speed. Its total fertility rate has dropped below replacement level; in Ho Chi Minh City, it has collapsed to an East Asian-style 1.51 births per woman. Vietnam’s demographic dividend will peak within the next decade, closing out its golden era of cheap, abundant factory hands by 2035. Vietnam faces getting old before it gets rich. If Hanoi cannot climb out of the low-margin foreign assembly trap and nurture domestic technology champions before its dependency ratios spike, its healthcare and pension costs will strangle state balance sheets before it ever sees high-income status.

Both Indonesia and Vietnam celebrate their national centenaries in the year 2045. Both have enshrined that year as the sacred deadline by which they must escape the middle-income trap and assume their seats in the pantheon of fully developed, high-income nations.
The verdict of compounding interest suggests that only one of them has a realistic chance of crossing the line.
Indonesia’s Visi Indonesia Emas 2045 will, in all probability, remain a lavish rhetorical brand. A nation that compounds at a steady 5%, will land in 2045 with a GDP per capita somewhere between $10,500 and $11,500. It will be an archipelago filled with shopping complexes, toll roads, and prosperous resource oligarchs, carrying considerable aggregate weight on the international stage. But it will still be an economy where the median citizen remains locked out of high-income living standards, held back by an education system that failed to train them and an elite that preferred digging holes to building factories.
Vietnam’s path to 2045 is narrower, fraught with geopolitical peril on the South China Sea, and complicated by a demographic clock whose hands are ticking down fast. Yet Vietnam possesses the single ingredient that every East Asian state that previously escaped the middle-income trap relied upon institutional discipline, a population armed with world-class foundational education, and a governing apparatus terrified of what happens if the export factories go quiet.
If, when the centenaries arrive in 2045, one of these two flags is flying outside the club of the world’s high-income economies, it will not belong to the G20 giant that spent three decades congratulating itself on its size. It will belong to the Leninist assembly floor that treated every economic benchmark as a matter of national survival… and achieved it.
StratEx - Indonesia Business Advisory provides Indonesia-focused advisory and leadership intelligence for investors that need to understand what is really moving beneath the surface. Contact us for better visibility before making your next move in Indonesia.