

If you wish to understand how economic policy is crafted in Indonesia, then this past week offered a clinic in split-screen government.
At one briefing, Finance Minister Suahasil Nazara stood before the press to explain why the state budget was sweating through its shirt.
Global oil shocks had pushed energy subsidies and compensation up 32 percent year-on-year to Rp 415.8 trillion by October.
Subsidized Pertalite petrol was still pegged at Rp 10,000 a liter even though its true cost had above Rp 18,000;
Subsidized diesel sat at Rp 6,800 against a real cost topping Rp 21,000.
Ten months into the year, the fiscal deficit had already hit Rp 379.3 trillion, tracking toward 2.85 to 2.9 percent of GDP, and close to Indonesia’s strict 3 percent statutory ceiling.
Across town, the Ministry of Manpower (Kemnaker) was in a far sunnier mood. Streaming a public briefing on its newly enacted Manpower Protection Law (Law No. 27 of 2026), Indah Anggoro Putri, the ministry’s director-general of industrial relations, unveiled what she called a “spectacular new regulation.” Under Article 253, medium, large, and foreign employers would soon be required to calculate potential severance liabilities from a permanent hire’s very first day on the payroll and hand the cash over to a centralized Severance Reserve Fund (Dana Cadangan Pesangon, or DCP). Private pension funds and corporate trusts, where many prudent firms already park worker reserves, would be barred from managing it. All severance pots, she told pension managers, would gather in one government institution by October 2027, ready to go live in 2028.
It took roughly twenty-four hours for Indonesian business circles and social media to connect the fiscal dots and whisper the word Danantara. It took another twenty-four hours for Danantara to issue an urgent denial saying it had never been tapped for the job, followed closely by Kemnaker sprinting backward to brand the Danantara rumors a “hoax.” No institution has been chosen, the ministry clarified. No contribution rate exists yet. No funding mechanism has been decided. Everything awaits a future Government Regulation, pending public consultations.
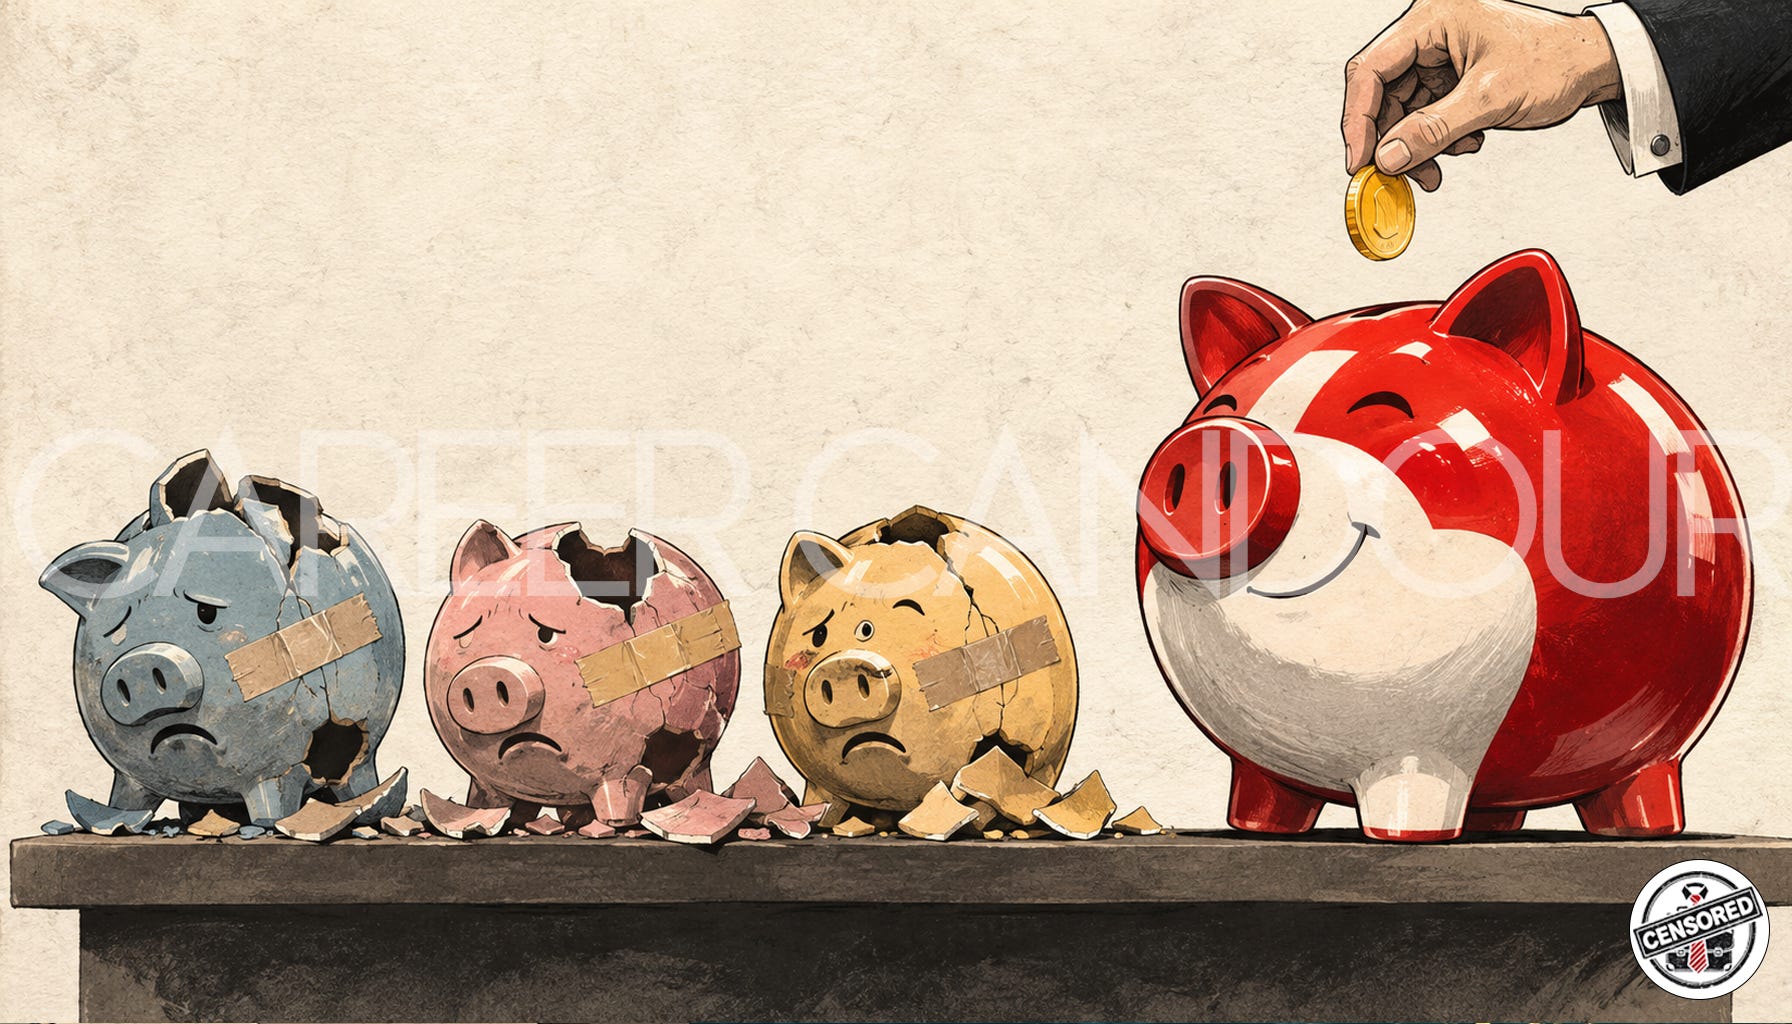
In other words, just over two weeks after the law took effect, Indonesia had legislated a mandatory nationwide transfer of corporate working capital into a single state vault whose name, rules, and legal safeguards remain to be determined. To sell a cash sweep that ambitious while insisting nobody look behind the curtain, Jakarta needed a compelling crime scene. Unfortunately for everyone involved, it has one.
The Sritex Excuse
To be fair to Indonesia’s lawmakers, the problem they claim to be solving is painfully real. Anyone who has watched a mid-sized factory fold knows the routine. An owner:
Hits financial distress,
Skips social-security payments,
Locks the gates,
…or in the worst industrial-park horror stories, boards a flight out of Soekarno-Hatta leaving behind leased machinery and a hundred unpaid employees holding worthless court rulings.
The poster child for Article 253 is PT Sri Rejeki Isman Tbk (Sritex), the once-mighty textile giant declared bankrupt in October 2024 before laying off more than 10,000 workers in early 2025. Nearly two years later, in late 2026, former Sritex workers are still waiting on roughly Rp 365 billion in severance claims. That is a moral failure, and it is easy to see why politicians pointed to Sritex and declared that bosses could no longer be trusted to hold severance promises on their own books.
But look closely at the actual paper trail from Sritex, and the alibi for a centralized state severance vault falls apart.
When Sritex shut its doors, Indonesia’s existing state-managed worker safety nets, JHT (old-age savings) and JKP (job-loss insurance) under BPJS Ketenagakerjaan, actually worked. Workers quickly received Rp 125 billion in JHT payouts alongside unemployment benefits. What stalled for two years was statutory severance, and it stalled for a legal reason that Article 253 does not fix: Indonesia’s 2004 Bankruptcy Law. Even after a 2013 Constitutional Court ruling bumped unpaid monthly wages ahead of bank mortgages, statutory severance still sits behind secured bank creditors in the liquidation queue, and the law imposes zero hard deadlines on bankruptcy curators to auction assets and pay workers. Curators dragged out auctions for years while banks stood at the front of the line. Ironically, Sritex’s desperate unions spent early November 2026 petitioning Danantara to buy out their bankrupt factories just so they might finally see their severance.
Worse, the severance reserve slipped into Law No. 27 of 2026 wasn’t even the product of a careful actuarial blueprint. A senior parliamentary committee deputy admitted in September that the centralized DCP clause was lawmakers’ own last-minute insertion; not something employer groups asked for, and not a true insurance guarantee. Look at the fine print of Article 253: the reserve is legally defined as a “source of payment,” not a state backstop. If a distressed company stops making deposits for eighteen months before going bust, the state pot comes up short anyway, and nobody covers the gap. Jakarta refused to rewrite the bankruptcy queue or insure tail-risk insolvencies. Instead, it decided to break the org charts of every healthy business in the country.

Advantage, Hanoi
Inside a real boardroom, nobody keeps bags of idle cash sitting in a corner equal to what it would cost to fire every employee tomorrow morning. Under standard accounting rules (PSAK 219), severance is a discounted, long-term actuarial promise, because most twenty-six-year-olds quit for a better offer long before they ever collect a 20-year layoff package. That capital doesn’t sit under a mattress; it buys inventory, funds machinery, and meets this month’s payroll.
Law No. 27 of 2026 takes a chainsaw to that basic corporate orthodoxy. Article 253 exempts only micro and small enterprises, defined as businesses generating up to Rp 15 billion (about $830,000) in annual revenue. That leaves Indonesia’s thin, credit-starved layer of fragile medium-sized businesses, and potentially all foreign-invested companies (PT PMAs). Because foreign entities are legally required to commit investment plans exceeding Rp 10 billion per business line, even a lean twelve-person foreign software subsidiary or regional consulting office can be legally classified as a “Large Enterprise” under these rules and swept straight into the severance-escrow net. Non-compliance escalates from business restrictions to license revocation under Article 253(7), backed by up to four years in prison and Rp 2 billion corporate fines under Article 295.
The reserve deposit also lands inside a labor code that simultaneously boarded up almost every legal exit door an executive team uses to manage headcount cycles. The new law abolished the old 0.5-times severance multiplier for business losses and bankruptcy, increased retirement payouts from 1.75 times to double basic severance, deleted “efficiency” as a standalone ground for layoffs, gutted operational outsourcing to little more than cleaning, catering, security, transport, and mining support, and cut fixed-term contracts from five years down to four.
Then comes the accounting ‘wrinkle’ nobody appears to have checked with the tax office. Under Article 9(1)(c) of Indonesia’s Income Tax Law, money placed into a “reserve fund” (dana cadangan) is explicitly non-deductible for the 22 percent corporate income tax outside a handful of exceptions like banks and mining reclamation. Upfront tax deductibility applies only to OJK-authorized pension funds like DPLKs. Unless Parliament rewrites the tax code, forcing companies to pull cash out of DPLKs and wire it into a government reserve means firms could pay cash into the state pot and still owe 22 percent corporate tax on that same money.
Drop that into an economy where Bank Indonesia has hiked its benchmark rate to 5.75 percent to defend a rupiah above Rp 18,000 per dollar, pushing commercial borrowing costs above 8.8 percent, and where the Deputy Investment Minister publicly conceded on November 11 that Indonesia’s Incremental Capital-Output Ratio (ICOR) sits at 6.8, meaning it takes nearly twice as much capital to generate a unit of output in Indonesia as in Vietnam (3.6).
Any competent CEO or chief people officer looking at that matrix knows exactly what happens next, and it isn’t a surge in permanent hiring. Firms will automate faster, split headcount into sub-threshold entities, shift roles into Article 102’s loosely regulated bucket for “partnerships” and digital gig contractors… or put the next regional expansion in Vietnam, which just clocked 9.95 percent GDP growth against Indonesia’s 5.47 percent. Indonesia doesn’t need a crystal ball to see where this ends: national statistics released on November 5 show 57.93 percent of Indonesia’s workforce is already informal, with informal employment growing two-and-a-half times faster than formal jobs over the past year. When you punish the formal sector for playing by the rules… they stop playing.

Trust Issues
Which brings us back to the weekend’s game of hot potato over who will actually sit on all this trapped cash.
There was nothing irrational about Indonesia’s suspicion that Danantara might end up holding the keys. Unlike Norway’s surplus-investing Oil Fund or Singapore’s GIC, Danantara is not a true sovereign wealth fund; it is a leveraged domestic superholding bundling 1,074 state-owned enterprises and subsidiaries with roughly $900 billion gross assets on paper to finance strategic national projects. It has not yet adopted the international Santiago Principles of transparency nor shed its reputation for opacity, missing deadlines for its 2025 consolidated accounts while operating under revised SOE laws that legally classify its staff as “not state administrators,” thus muddying routine audit and anti-corruption boundaries. When Parliament revised the financial sector law earlier in 2026 to let Danantara issue “Patriot Bonds” carrying Article 50A immunity from tax audits and legal scrutiny for primary buyers and then sacked the previous finance minister in September just days after he demanded Rp 120 trillion in profits from Danantara, investors learned that in a fiscal pinch, state liquidity pools tend to become state financing tools.
Even if Danantara never touches a rupiah of corporate severance, Indonesia’s history with state-pooled worker funds reads like a warning label.
Asabri, the pension and insurance pool for soldiers and police, lost Rp 22.78 trillion to manipulated junk stocks.
Jiwasraya imploded in a Rp 16.8 trillion-plus solvency scandal requiring a taxpayer rescue.
Taspen, the civil-service pension giant, suffered a fictitious-investment corruption scandal whose former CEO saw his ten-year prison sentence upheld by the Supreme Court just this past mid-year.
Small wonder that when Jakarta tried to mandate a 3 percent payroll deduction for the Tapera housing fund, workers revolted and the Constitutional Court ruled that the law would be an unconstitutional forced savings scheme, if not reorganised within 2 years.
Yet even assuming saintly fund managers, the math inside Article 253 is broken by design. Severance in Indonesia is a defined-benefit multiple of an employee’s final salary. If provincial minimum wages and promotions push nominal pay up 7 to 9 percent a year, while a cautious state manager parks severance cash in domestic government bonds yielding 6 percent, the reserve falls behind reality every single year, leaving employers with an endless compounding top-up bill anyway. Meanwhile, the law contains zero statutory deposit guarantee (nothing like Indonesia’s LPS bank-deposit insurer) if the state manager loses money, no clear provision to release frozen cash during the extended court battles triggered by Article 235’s rule keeping fired workers on full payroll, and no escheat guardrails to handle billions in unclaimed balances.

How Others Do It
Whenever foreign investors point out these flaws, officials in Jakarta routinely reply that Indonesia is “unique.” That defense works… until you check what Indonesia’s neighbors and peer economies actually do.
Across ASEAN, nobody is building a giant, monopolistic state severance escrow.
Vietnam solved unfunded corporate defaults years ago by moving in the exact opposite direction: it introduced a 1 percent employer (and 1 percent employee) Unemployment Insurance contribution and deducts years covered by that insurance directly from the employer’s severance liability.
Thailand does have a state Employee Welfare Fund to cover unpaid severance and wages, yet set the rate at 0.25 percent, explicitly exempts companies using private licensed provident funds, and postponed launch twice (most recently in October 2026, pushing it to January 2027) to avoid squeezing cash-strapped firms.
Cambodia, plagued by the same runaway garment-factory closures as West Java, bypassed state coffers altogether in 2019 by forcing factories to pay 7.5 days of seniority pay directly to workers every six months, thus eliminating runaway arrears and state middlemen.
Singapore has no statutory severance law at all, relying on portable retirement savings and targeted SkillsFuture jobseeker cash.
Zoom out to the OECD, and the evidence is clear: do not freeze 100 percent of healthy companies’ capital to insure against the 1 percent that go bankrupt.
Germany solves insolvency risk with a 0.15 percent payroll levy (Insolvenzgeld).
South Korea runs a 0.09 percent Wage Claim Guarantee Fund to pay workers immediately upon corporate collapse and chase the bankrupt estate later, while letting companies fund regular severance pensions through competing private financial institutions.
Britain, Canada, and Australia pay laid-off staff out of general insurance or tax-backed last-resort funds (London turns claims around in an average of eleven days) and subrogate into bankruptcy proceedings.
Even Austria, which in 2003 cured an Indonesian-style lump-sum severance cliff that had paralyzed corporate mobility, fixed it by scrapping the back-loaded payout in favor of a flat 1.53 percent monthly deposit into competing, regulated private worker-owned accounts.
In fact, there is only one major emerging market on Earth that built what Indonesia is flirting with right now: Brazil, whose 1966 FGTS forced employers to wire 8 percent of payroll into worker accounts controlled by a single state-owned bank, Caixa Econômica Federal. For decades, Brazil used that captive mountain of cash to subsidize state housing and public works while crediting workers a dismal 3 percent plus a near-zero reference rate, thus inflating away workers’ real severance wealth until Brazil’s Supreme Court finally intervened in 2024 to mandate inflation indexing. Brazil didn’t prove the model works; it proved what happens when a deficit-prone state is handed a captive corporate piggy bank.

Who Benefits?
If virtually no successful economy pools private severance into a single state monopoly, and the one large peer that tried spent sixty years repenting, why is Indonesia?
Strip away the compassionate press releases, and Article 253 looks like the offspring of two familiar Jakarta instincts:
Populist labor optics on the surface, and
Insider capital hoarding underneath.
Labor unions get statutory multipliers on paper, while lawmakers get to look tougher than Sritex’s owners without touching a Bankruptcy Law that protects bank collateral. Meanwhile, the biggest beneficiaries inside the corporate ecosystem are entrenched mega-conglomerates and state-owned enterprises. Giants with deep treasuries, state-bank access, and special-zone privileges can absorb working-capital drag while watching compliance complexity price out nimble mid-market domestic rivals and cautious foreign entrants. And if that trapped private cash ends up buying sovereign bonds or strategic state debt, the fiscal apparatus gets a captive domestic lender just as energy subsidies bite.
Ten days from now, OECD Secretary-General Mathias Cormann arrives in Jakarta to advance Indonesia’s bid for full OECD membership by 2028—just weeks after the OECD’s October governance review explicitly warned Indonesia about blurred boundaries between state ownership, Danantara, and competitive neutrality. Yet Kemnaker calmly talked about stripping severance-management mandates out of private, OJK-regulated pension providers and handing a state monopoly exclusive custody by late next year.

None of this means Indonesian workers should be left to the mercy of bankrupt textile barons or vanishing factory owners. Fixing the Sritex problem isn’t mysterious or expensive. Jakarta could pass a bulletproof solution tomorrow:
Elevate statutory severance above secured bank debt in bankruptcy court so lenders start policing corporate solvency before factories lock their doors;
Convert a sliver of existing payroll levies (à la South Korea’s 0.09 percent) into a fast-disbursing insolvency backstop under BPJS Ketenagakerjaan; and
Mandate ring-fenced, bankruptcy-remote trust accounts across competing, OJK-regulated private DPLKs and custodian banks, giving workers security without handing politicians a single centralized vault.
Instead, Indonesia has handed its businesses and workers a legally binding ultimatum. Until the implementing regulation drops, every CFO finalizing 2026 audits, every foreign investor pricing a plant in Java versus Ho Chi Minh, and every HR director rethinking permanent headcount is staring at the same absurd demand: prepare to wire your company’s cash into a vault whose name, tax status, deposit rate, and legal guarantee remain strictly to be determined.
If that is what a “spectacular” worker protection looks like, one shudders to think what an ordinary one does.
StratEx - Indonesia Business Advisory provides Indonesia-focused advisory and leadership intelligence for investors that need to understand what is really moving beneath the surface. Contact us for better visibility before making your next move in Indonesia.